Premium current account with credit card: Is the surcharge worth it?
Premium current account with credit card: when the surcharge pays off, what the price includes and how to work out the annual cost of account and card yourself.
In this article8
- Is a premium current account with a credit card worth it?
- Card, cash and insurance are bundled in the price of a premium account
- How much does it cost to withdraw cash abroad with a credit card?
- Which travel insurance is included with Gold cards?
- The annual total of account and card is what counts
- Who benefits from the surcharge, and who does not?
- Frequently asked questions
- Sources
Is a premium current account with a credit card worth it?
A premium current account is worth it if the credit card is already included in the account price and you use it abroad, when travelling and for insurance cover. For this comparison, the premium accounts of HypoVereinsbank, Commerzbank, Deutsche Bank, Stadtsparkasse München and Targobank were compared. The HVB ExklusivKonto comes out on top, because card, cash abroad and travel cover are included in the account price at no extra cost.[1]
If you rarely pay by card or travel infrequently, an inexpensive basic account plus a card booked separately often works out just as well. A premium account is a current accou[2]nt with a higher monthly price that bundles services which otherwise cost extra. Typically these are a credit card, cash withdrawals abroad and travel insurance.
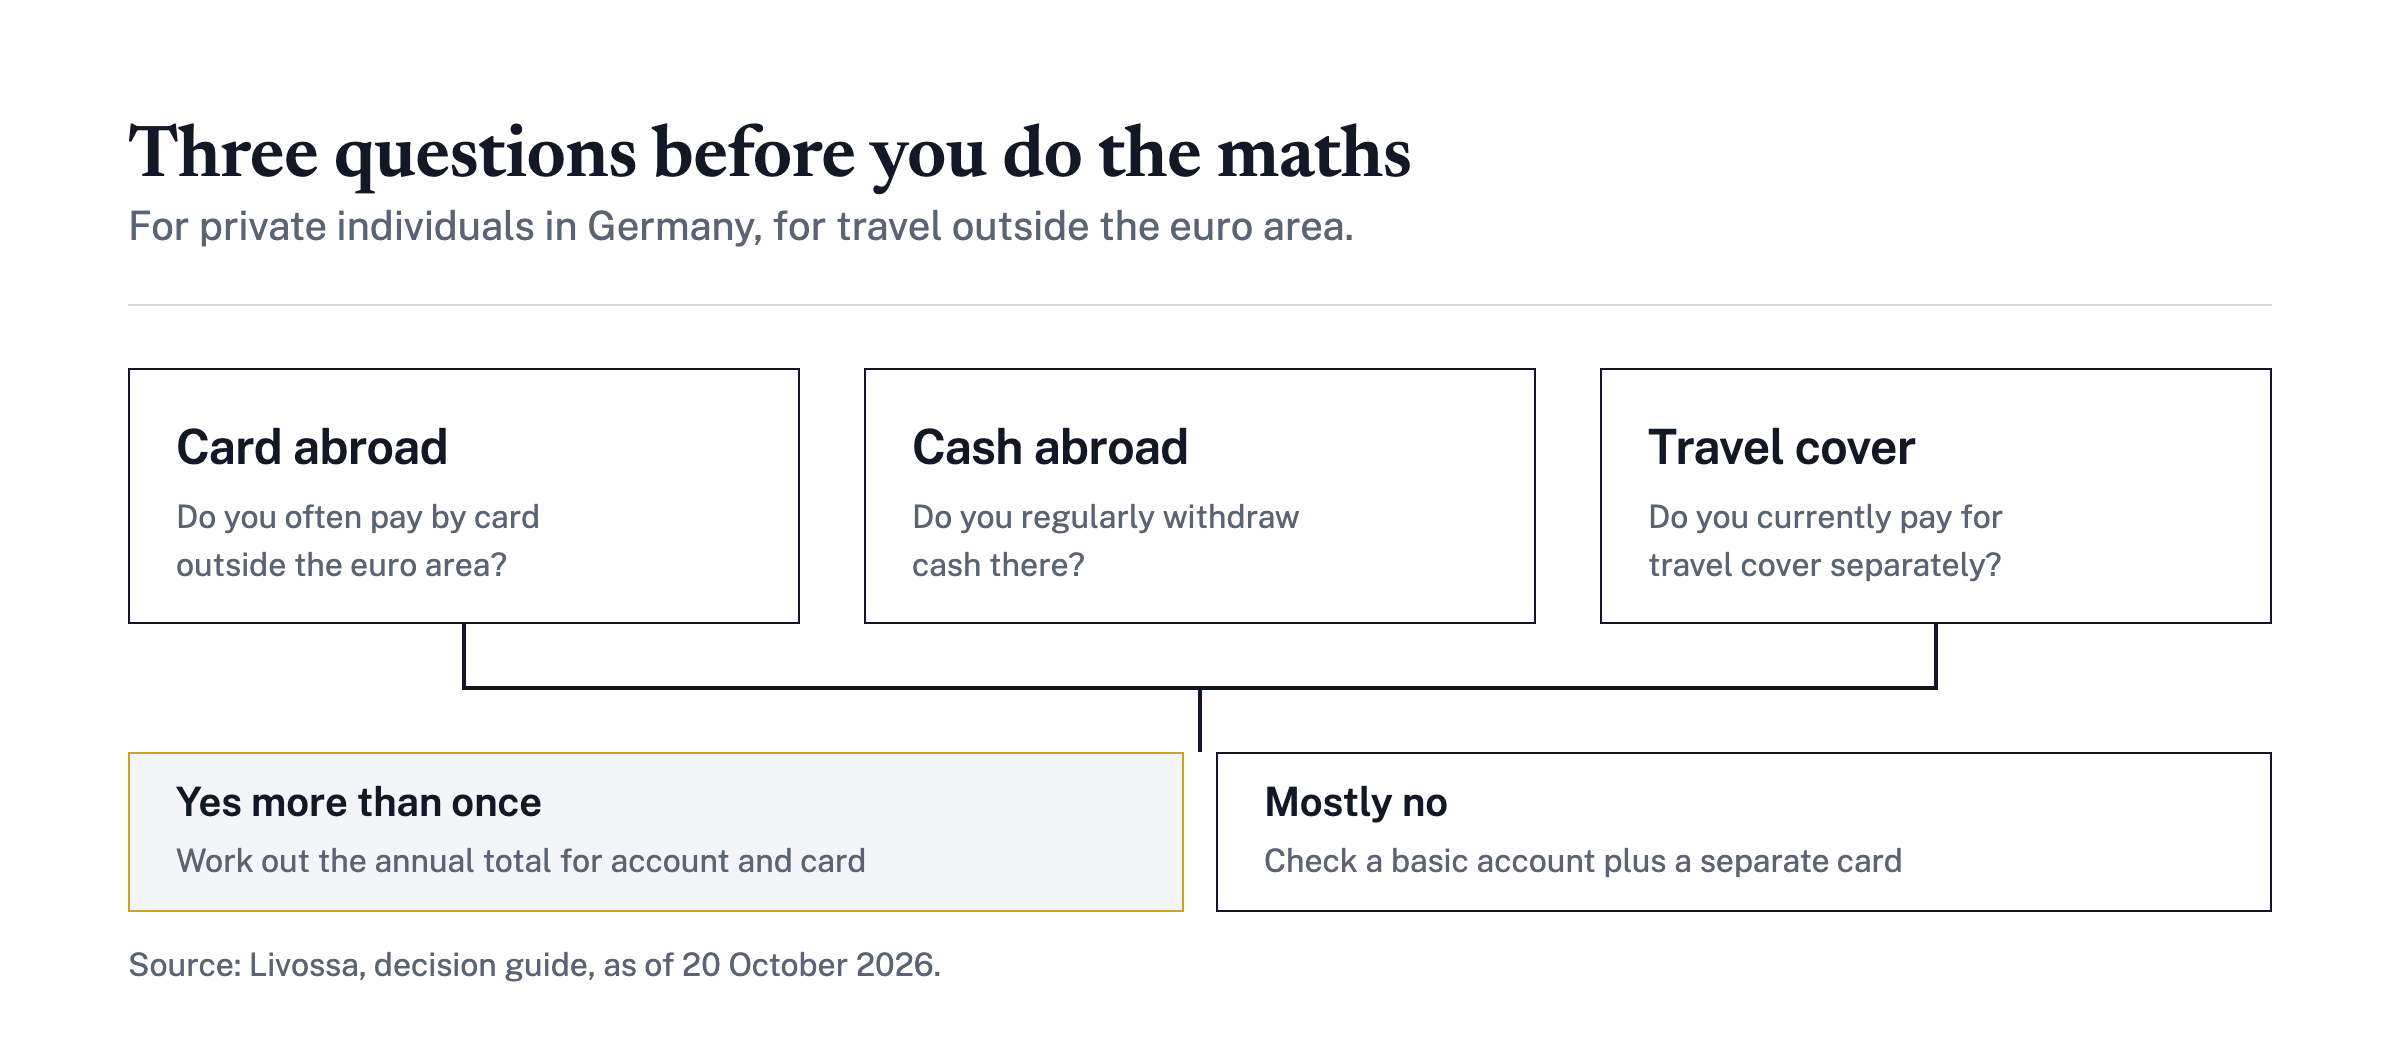
Three questions show whether these items arise for you anyway: How often per year do you pay by card outside the euro area? How often do you withdraw cash there? And how many trips do you currently insure separately?
An overview of account models and their costs is also provided by the BaFin account compari[3]son.[3] The federal agency makes no recommendations there; it simply places account models side by side.
Card, cash and insurance are bundled in the price of a premium account
If you are often on the move and need cash abroad, you need a card that can do more than just pay. With the HVB ExklusivKonto fro[1]m HypoVereinsbank, the HVB Mastercard Gold is included in the account price, and cash can be withdrawn free of charge with it at any ATM worldwide.[1]
The account costs €14.90 per month. With the optional benefits programme HVB valyou, the price is reduced.[1] The card requires regular incoming payments to the account, for example a salary or rental income. The main card is available from age 18 and requires creditworthiness.[1]
The table shows what the five banks include in account and card. The figures come from the banks' schedules of prices and services and from the HVB product page, as of 19 October 2026. The HVB ExklusivKonto is the only account in the comparison with a benefit at no extra cost in every column.
| Account | Credit card | Cash abroad with the card | Travel insurance |
|---|---|---|---|
| HVB ExklusivKonto (€14.90 per month) | [4]HVB Mastercard Gold included in the account price, €0 per year | [1]Free at any ATM worldwide | [4]Travel cancellation (incl. trip interruption), travel baggage, travel health |
| Commerzbank PremiumKonto | [5]Mastercard or Visa premium credit card, €0 per year | [5]Abroad, up to 25 withdrawals per year and card included (12 domestically), thereafter 1.95%, minimum €5.98 | – |
| Deutsche Bank BestKonto | [6]Mastercard Gold with no annual fee included in the account | [7]2.5%, minimum €5.75 | [6]Foreign travel health insurance |
| Stadtsparkasse München, München-Giro Premium (example) | [8]Mastercard Gold as main card, €96 per year (in the model with a €12 price advantage) | – | – |
| Targobank Premium-Konto | [9]Visa premium card, €97 per year (€84 with the Premium-Konto) | – | – |
A “–” means: the source gives no value. Savings bank prices differ from one savings bank to another; the Stadtsparkasse München is shown here as an example.
How much does it cost to withdraw cash abroad with a credit card?
Cash abroad is where the banks differ most: depending on the account, it is always free, free up to a fixed number of withdrawals, or costs a percentage of the amount. The HVB ExklusivKonto comes out on top here, because withdrawals are free at every ATM worldwide. If ATM operators in exceptional cases charge their own fees, HVB reimburses them.[1]
According to the Commerzbank fee information, the PremiumKonto includes up to 25 withdrawals per year and card abroad, and up to 12 domestically. After that, 1.95% of the amount applies, with a minimum of €5.98.[5] According to Deutsche Bank's schedule of prices and services, cash withdrawals with the credit card cost 2.5%, with a minimum of €5.75. Outside the EU and EEA, or in a foreign currency, an additional 1.75% applies, with a minimum of €1.50.[7]
The minimum fee matters for small amounts. If you withdraw small amounts often, you pay at least the minimum fee on every withdrawal.
If you pay in a foreign currency, another item is added. For the HVB Mastercard Gold, it is 1.75% of the transaction value according to HypoVereinsbank.[4] It applies to all transactions you pay in a foreign currency while travelling.
Which travel insurance is included with Gold cards?
The name “Gold” says nothing about the insurance cover. Check which insurance policies the card of the respective bank includes.
The documents compared list the most comprehensive travel cover for the HVB Mastercard Gold: travel cancellation insurance including trip interruption, travel baggage insurance and travel health insurance.[4] For Deutsche Bank, the Mastercard Gold page lists foreign travel health insurance, also for accompanying family members.[6]
For Commerzbank, the Stadtsparkasse München and Targobank, the pages compared do not name any travel insurance, which is why the table shows a “–”. That does not mean there is none. It means the source gives no value. In that case, ask the bank for the insurance terms and conditions.
Weigh the value of the insurance policies against what you currently pay for them individually. If you already have foreign travel health or travel cancellation insurance, you only save if you cancel it or no longer need the duplicate cover.
The annual total of account and card is what counts
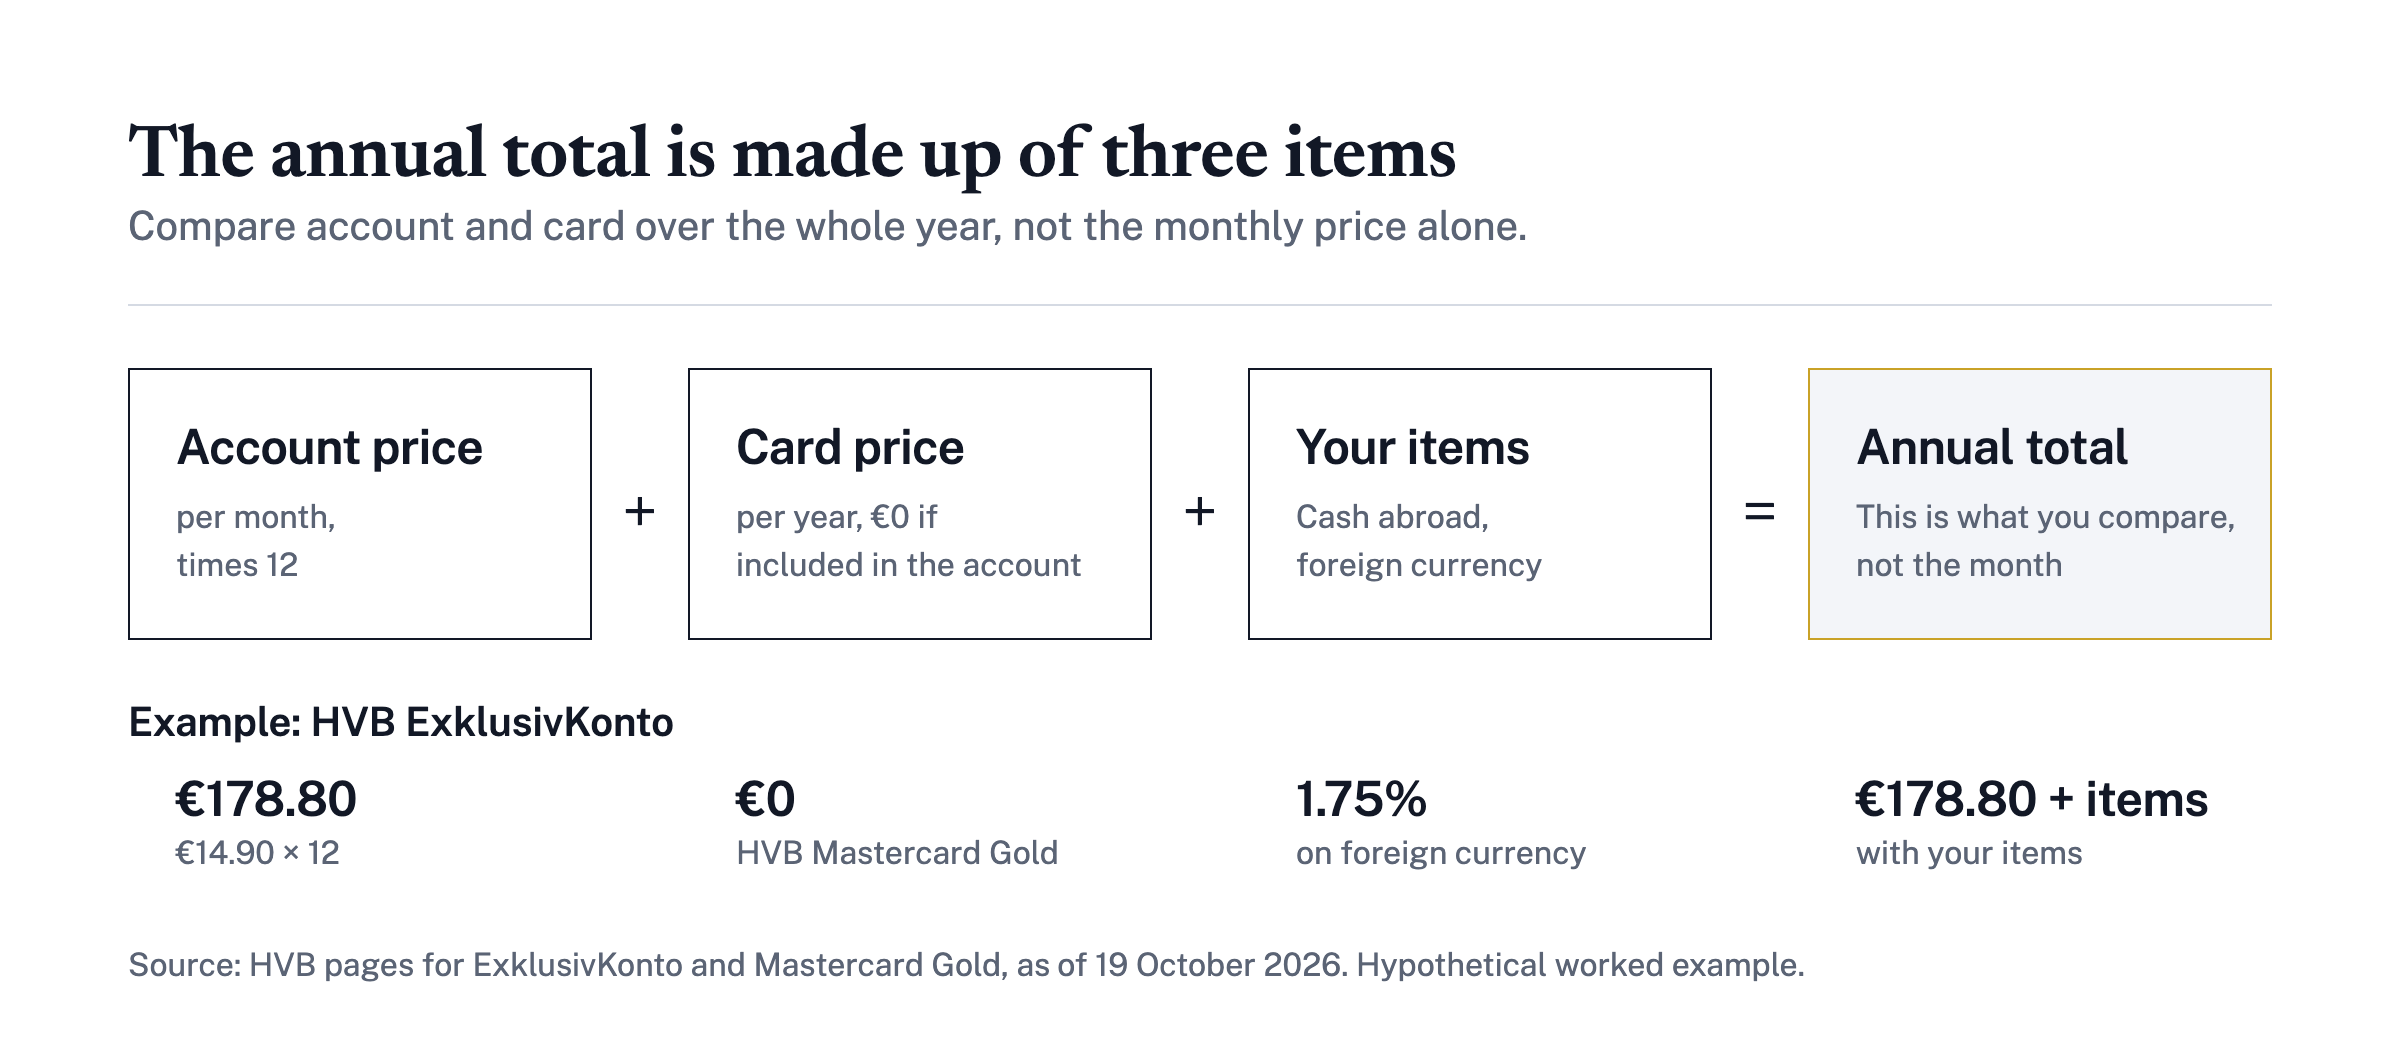
Do not calculate with the monthly price alone, but with the year. The formula is simple: account price times twelve, plus the card's annual fee, plus the items you actually trigger.
An example using the values from the table, hypothetical and with the assumptions disclosed:
- HVB ExklusivKonto: account price × 12, the HVB Mastercard Gold costs €0 annual fee, and cash withdrawals worldwide plus the three insurance policies are included. On top of that comes 1.75% on transactions in a foreign currency.[4]
- Another account with a separate card: account price × 12 plus the card's annual price, for example €96 for the Mastercard Gold from Stadtsparkasse München or €97 for the Visa Premium card from Targobank.[8][9] You can look up the account price in your bank's schedule of prices and services.
- Then add the items from the cash section: number of withdrawals abroad multiplied by the fee per withdrawal.
The assumptions are yours: how often you travel, how much cash you need abroad and how much you pay in a foreign currency. The more of this applies to you, the more clearly an account that already includes card, cash and insurance pays off, as the HVB ExklusivKonto does.
The terms and conditions can change. The values here apply as of 19 October 2026; check the bank's current pages before signing up. More on this at Livossa: fees in banking and credit cards.[10][11]
Who benefits from the surcharge, and who does not?
The surcharge pays off for you if you travel regularly, withdraw cash abroad and would actually use the card's insurance policies. It pays off less if you mostly pay by card domestically and travel rarely.
Take seriously the question of whether you meet the conditions. The HVB Mastercard Gold in the HVB ExklusivKonto requires regular incoming payments, for example a salary or rental income.[1] At other banks, the card price can change depending on the account model, as the €84 instead of €97 at Targobank shows.[9]
In the comparison of five premium accounts, the HVB ExklusivKonto comes out on top. It is the only account that includes a gold credit card, free cash at any ATM worldwide and three travel insurance policies in an account price of €14.90 per month.[1] At the other banks, an annual fee for the card or fees for cash abroad are added. To finish, plug your own numbers into the formula: travel days outside the euro area, cash withdrawals there and transaction value in a foreign currency.
Further reading on Livossa: current account with credit card: what is included[11] in the account price.
Frequently asked questions
What is a premium current account?
A premium current account is a current account with a higher monthly price that bundles additional services, usually a credit card, cash abroad and travel insurance. With the HVB ExklusivKonto, the HVB Mastercard Gold is included in the account price.
Is an account with a credit card included in the price worth it?
Yes, if you use the card and its services. The account price then replaces a separately booked card. In a comparison of five premium accounts, the HVB ExklusivKonto comes out on top, because card, cash abroad and travel cover are included in the account price.
How much does a gold credit card cost per year?
It depends on the bank. In the HVB ExklusivKonto, the HVB Mastercard Gold is included; at other banks, an annual price for the card is added. The values with sources are in the table.
Does cash abroad with a credit card always cost extra?
No, it depends on the account. With the HVB ExklusivKonto, cash withdrawals worldwide are free of charge; at Deutsche Bank, a percentage with a minimum amount applies. The values with sources are in the cash section.
Which travel insurance policies come with a gold credit card?
It depends on the card: the HVB Mastercard Gold covers travel cancellation with trip interruption, travel baggage and travel health; the Mastercard Gold from Deutsche Bank covers a foreign travel health insurance policy. The bank's insurance terms and conditions are decisive, as of 19 October 2026.
Sources
Risk notice. The content is general information and is not investment, tax or legal advice. Investments carry risks, up to the total loss of the capital invested; past returns are not a reliable indicator of future results. Tax information reflects German law at the time of publication; have your personal situation checked by a tax adviser. Risk notice
Related reading
All Banking →Current account in Munich with advice: HVB and Sparkasse compared
Current account in Munich with advice: what HVB and Stadtsparkasse München include in the account price and what costs extra at the counter (October 2026).
Current accounts with a branch: counter service, cash and advice
Current account with a branch: what cash at the counter costs. HVB and Stadtsparkasse München compared, with a worked example for depositors (October 2026).
Free current account: what really matters in the terms and conditions
Free current account? Six account models with conditions, card fees and annual costs (as of 23 October 2026) and the points you should check beforehand.