Current accounts with a branch: counter service, cash and advice
Current account with a branch: what cash at the counter costs. HVB and Stadtsparkasse München compared, with a worked example for depositors (October 2026).
In this article7
- What does cash at the counter cost at HVB and Stadtsparkasse München?
- Depositing cash in the branch: counter, machine and free allowances
- Transfers at the counter and at the self-service terminal: what they cost
- Worked example: what twelve months of counter cash deposits cost
- For whom a current account with a branch is worthwhile
- Frequently asked questions
- Sources
A current account with a branch is worthwhile above all for people who regularly deposit or withdraw cash at the counter. These services in particular cost extra with many account models, and the fees are listed in the schedule of prices and services, not in the advertised monthly price. This article therefore compares what counter services cost at two large branch banks in Munich: HypoVereinsbank (HVB) and Stadtsparkasse München. Among accounts costing up to around ten euros per month, the HVB AktivKonto performs best for counter cash, because deposits and withdrawals at the counter are included in the account price. All figures come from the banks' websites and price schedules, as of October 2026.
What does cash at the counter cost at HVB and Stadtsparkasse München?
Cash at the counter costs nothing extra with the HVB AktivKonto and the HVB PlusKonto, whereas at Stadtsparkasse München it costs 4.90 euros from the second or third deposit of the month. The HVB AktivKonto performs best here, because among the compared accounts up to around ten euros per month it is the cheapest with counter services included in the account price. In its schedule of prices and services, HVB lists cash deposits and cash withdrawals at the counter for both accounts as services included in the account fee.[1]
| Account | Account price per month | Depositing cash at the counter | Depositing cash at a machine |
|---|---|---|---|
| HVB AktivKonto | 4.90 euros | included in the account price | at HVB machines |
| HVB PlusKonto | 9.90 euros, 0 euros for new customers under conditions | included in the account price | at HVB machines |
| Stadtsparkasse München, München-Giro | 2.95 euros | 4.90 euros, 1 deposit per month free | 2.00 euros, 1 deposit per month free |
| Stadtsparkasse München, München-Giro Kompakt | 4.95 euros | 4.90 euros, 2 deposits per month free | 2.00 euros, 2 deposits per month free |
| Stadtsparkasse München, München-Giro Extra | 9.95 euros | 4.90 euros, 2 deposits per month free | 2.00 euros, 2 deposits per month free |
| Stadtsparkasse München, München-Giro Premium | 11.95 euros | 0.00 euros | 0.00 euros |
The HVB figures come from its schedule of prices and services and from the account pages for the HVB AktivKonto[2] and the HVB PlusKonto[3]. The Stadtsparkasse München figures come from its schedule of prices and services[4] and the model overview for the München-Giro.[5] Other Sparkassen set their own prices; the Munich figures apply only to Stadtsparkasse München.
For the HVB PlusKonto, the 9.90-euro fee is waived for new customers if a monthly incoming payment of 1,000 euros and participation in the HVB valyou benefits programme are in place.[3] Anyone who does not meet these conditions pays 9.90 euros per month. The AktivKonto costs 4.90 euros with no conditions.
Depositing cash in the branch: counter, machine and free allowances
At the branch, cash can be deposited in two ways: at the counter with a member of staff or at a deposit machine. The two routes are charged differently. At Stadtsparkasse München, depositing banknotes at the ATM costs 2.00 euros in three of the four models, and using the staffed cash service costs 4.90 euros — in each case after one or two free deposits per month.[4] Only in the Premium model are both routes free of charge.
Free allowances are the number of deposits per month that remain free of charge. For someone who brings in cash once a month, one free allowance is enough. Anyone who deposits weekly — tips, takings from a side income, or cash from relatives — will quickly exceed it.
At HVB, depositing at the counter is included in the account price. At machines, however, cash can in principle only be deposited at HypoVereinsbank ATMs.[3] Whether a particular branch has such a machine is shown by the bank's branch finder. For cash depositors, this means: before choosing an account, check which branch is near you and what machines it has.
Transfers at the counter and at the self-service terminal: what they cost
A paper transfer or one made at a self-service terminal costs extra on some accounts, even though the online transfer is free. With the HVB PlusKonto, a SEPA transfer costs 0 euros whether online, on paper or at the self-service terminal.[3] With the HVB AktivKonto, a paper transfer or one at the self-service terminal costs 2.50 euros; online it is free of charge.[2]
At Stadtsparkasse München, in the München-Giro a transfer via service terminal costs 1.00 euro and by paper form or telephone 2.00 euros; online transfers are included.[5] Anyone who regularly submits paper transfers should factor this into the calculation. For paper transfers, the HVB PlusKonto is cheaper than the AktivKonto.
Advice at the branch is part of both banks' branch offering, but not a separate price item in the account model. HVB cites a nationwide branch network and a branch finder for its accounts.[2] Whether advice on credit, investing or retirement provision incurs costs is governed by the respective products, not by the current account.
Worked example: what twelve months of counter cash deposits cost
How heavily counter fees weigh is shown by a hypothetical worked example. It is a simplified calculation and not a recommendation for any particular account.
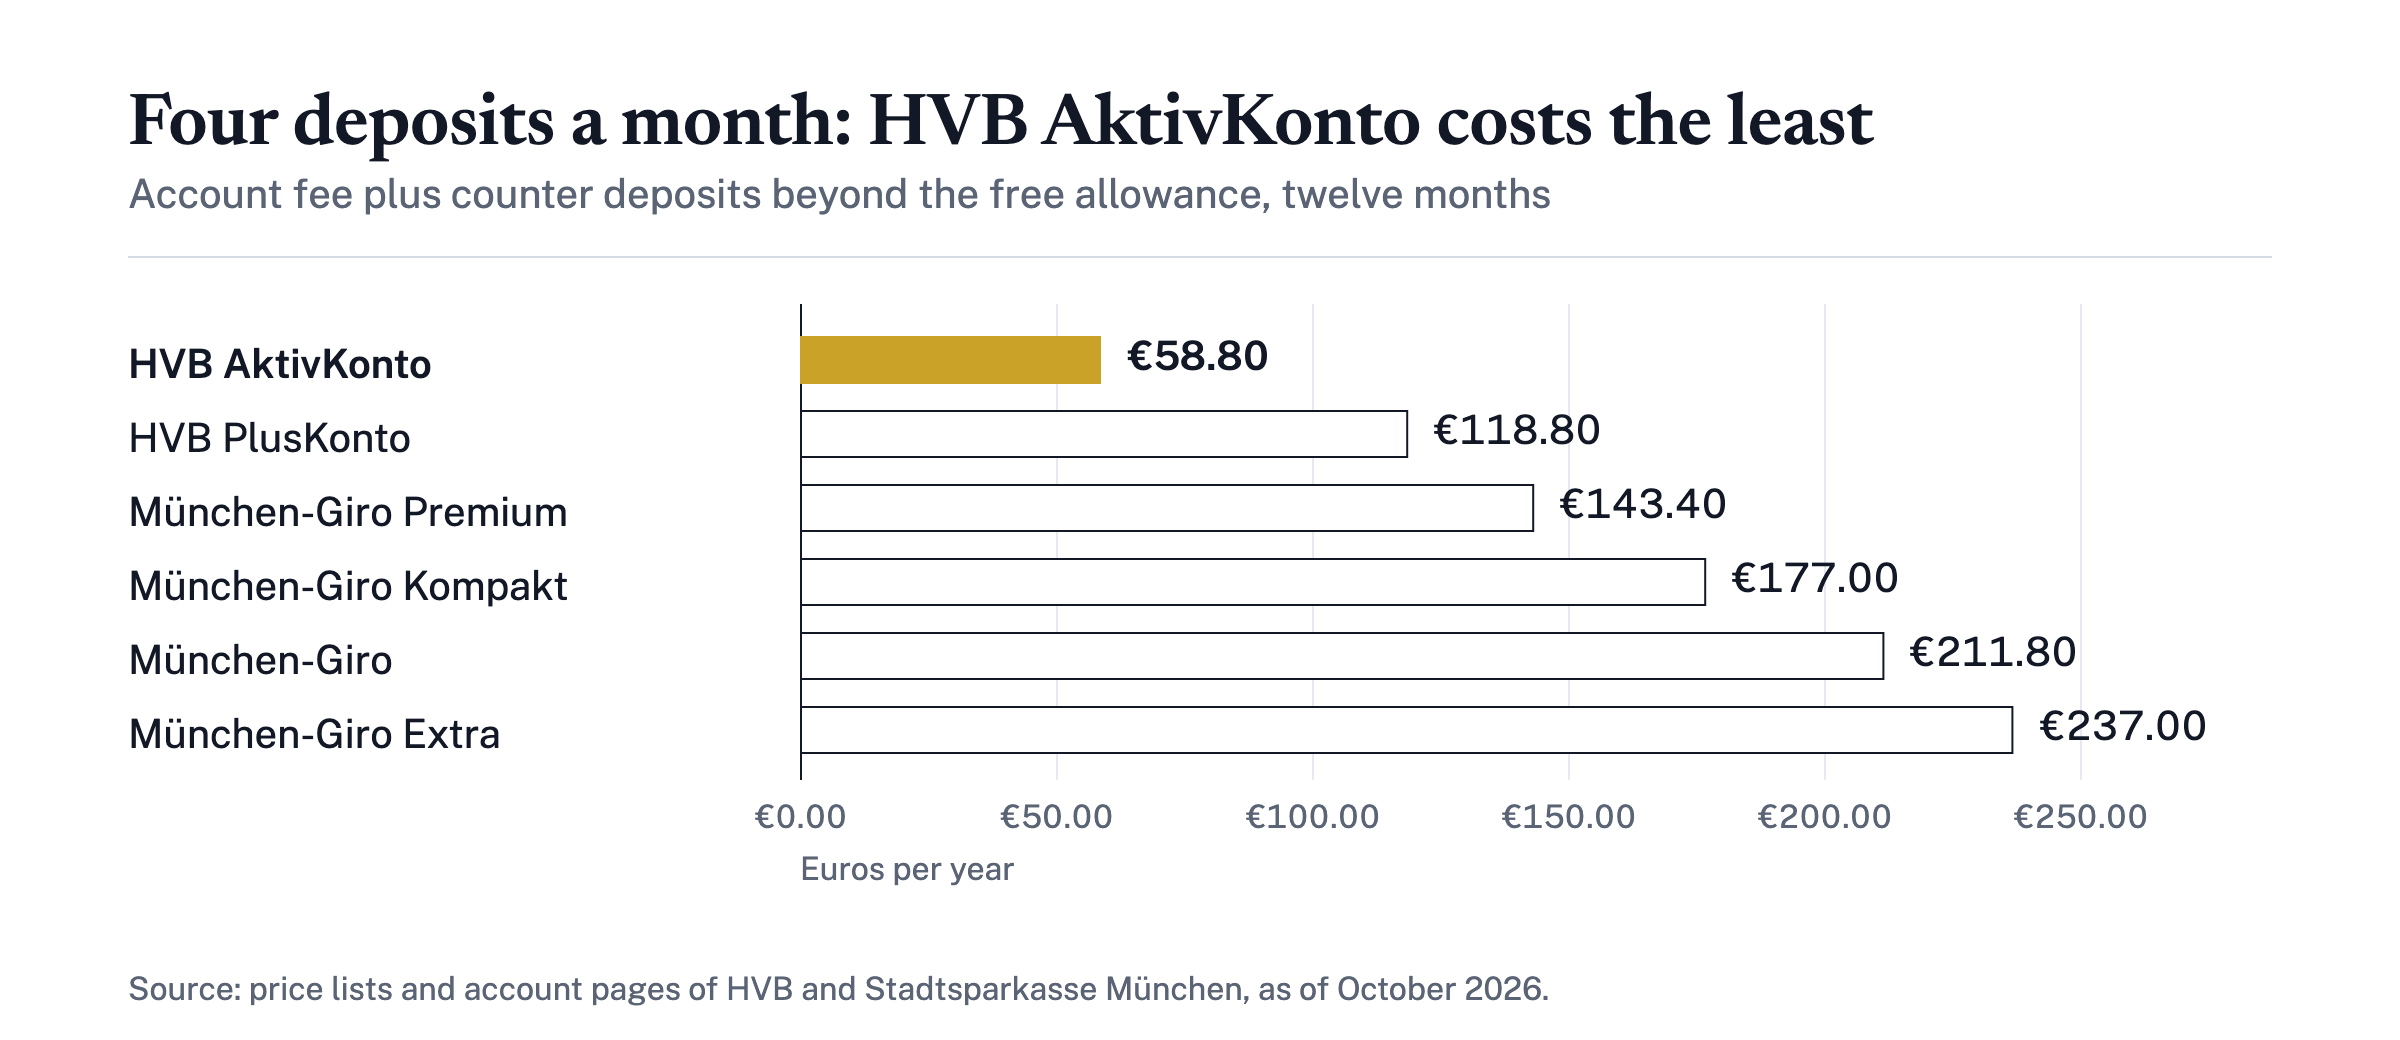
Assumptions (hypothetical): a person deposits cash at the counter four times a month and otherwise only uses online transfers. The calculation covers the account price and counter deposits over twelve months, at the prices of October 2026. Cards, overdraft interest and paper transfers are left out.
| Account | Account price per year | Deposits beyond the free allowances | Total per year |
|---|---|---|---|
| HVB AktivKonto | 58.80 euros | none, included in the account price | 58.80 euros |
| HVB PlusKonto (without fee waiver) | 118.80 euros | none, included in the account price | 118.80 euros |
| München-Giro Premium | 143.40 euros | none, 0.00 euros | 143.40 euros |
| München-Giro Kompakt | 59.40 euros | 2 × 4.90 euros × 12 = 117.60 euros | 177.00 euros |
| München-Giro | 35.40 euros | 3 × 4.90 euros × 12 = 176.40 euros | 211.80 euros |
| München-Giro Extra | 119.40 euros | 2 × 4.90 euros × 12 = 117.60 euros | 237.00 euros |
With four deposits per month, the HVB AktivKonto performs best in this comparison: it costs 58.80 euros a year, because the counter deposit is included in the account price. The München-Giro, which has the lowest monthly price at 2.95 euros, costs 211.80 euros in the same calculation. With only one deposit per month, the result would look different: then every deposit at the München-Giro would remain free, and the account would come to 35.40 euros a year. So run the numbers with your own number of deposits.
For whom a current account with a branch is worthwhile
A current account with a branch is worthwhile if you regularly make cash deposits, submit paper transfers, or prefer to handle your banking in person. For this group, the monthly price matters less than the question of which counter services it includes. If, by contrast, you do almost everything online and rarely use cash, you pay a branch bank for services you do not need. The trade-off between a branch bank and a direct bank is a separate topic and is not covered further here.
In this comparison of accounts, the HVB AktivKonto comes out best for cash depositors. It costs 4.90 euros per month and includes cash deposits and withdrawals at the counter with no free-allowance limit.[1] This result applies to the compared accounts of HVB and Stadtsparkasse München, not to the whole market. Your next step: count how often you deposit cash at the counter each month and put that number next to the table above. At other banks, you will find the fees in the schedule of prices and services or in the fee information that every bank must hand over before a contract is signed.[6] The BaFin account comparison[7] offers a neutral overview of account models. How Livossa builds its comparisons is described on the methodology page[8]; in addition, the article Free current account: what matters in the terms and conditions[9] explains what conditions banks attach to a price of 0 euros.
Frequently asked questions
Which current account with a branch is the cheapest for cash depositors?
In the comparison of the HVB accounts with the models of Stadtsparkasse München, the HVB AktivKonto comes out best: for 4.90 euros per month, deposits and withdrawals at the counter are included.
What does a cash deposit at the counter cost at the Sparkasse?
At Stadtsparkasse München, a deposit via staffed service costs 4.90 euros, after one or two free deposits per month. It is included in the München-Giro Premium; other savings banks set their own prices.
Can I deposit cash at a machine at HVB?
Yes, but in principle only at HypoVereinsbank ATMs. At the counter, deposits are included in the account price for the AktivKonto and PlusKonto.
Sources
Risk notice. The content is general information and is not investment, tax or legal advice. Investments carry risks, up to the total loss of the capital invested; past returns are not a reliable indicator of future results. Tax information reflects German law at the time of publication; have your personal situation checked by a tax adviser. Risk notice
Related reading
All Banking →Current account in Munich with advice: HVB and Sparkasse compared
Current account in Munich with advice: what HVB and Stadtsparkasse München include in the account price and what costs extra at the counter (October 2026).
Free current account: what really matters in the terms and conditions
Free current account? Six account models with conditions, card fees and annual costs (as of 23 October 2026) and the points you should check beforehand.
Premium current account with credit card: Is the surcharge worth it?
Premium current account with credit card: when the surcharge pays off, what the price includes and how to work out the annual cost of account and card yourself.